

Military Retirement analysis by Appwee
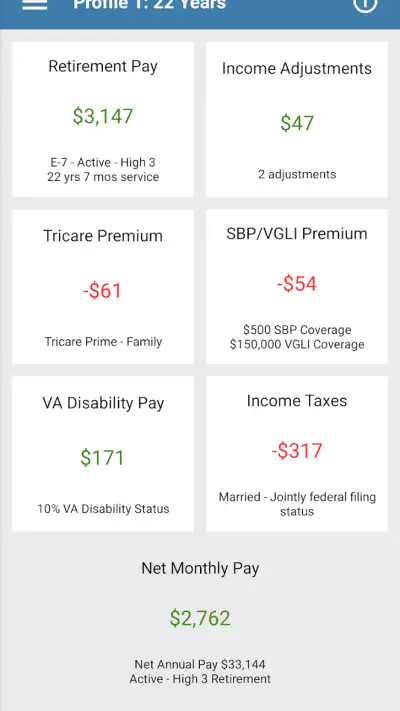
Planning military retirement is one of those jobs that looks simple until several service details, pay assumptions, and household decisions begin pulling in different directions. I found Military Retirement useful because it gives that planning process a focused place on a phone instead of leaving every estimate scattered across notes, spreadsheets, and conversations. It is a finance app from LYNNFIELD LLC, built specifically around estimating military retirement pay, and that narrow purpose is also its biggest strength.
I would not treat it as an official pay determination or as a replacement for checking current military guidance. I would use it as a practical planning calculator: something to open when I want to test a scenario, explain an estimate to someone at home, or prepare better questions before speaking with a qualified benefits adviser. That distinction matters, especially when the result could influence housing, employment, debt repayment, or a decision about when to leave service.
How it fits into a shared household planning routine
The most convincing use case is not a solo session lasting an entire afternoon. It is a short, shared review at the kitchen table. One person can enter or adjust the service assumptions while a spouse or partner watches the estimate and asks the questions that are easy to overlook: What changes if retirement happens later? Which income figure are we actually using? Are we discussing a rough monthly amount or building a complete household budget?
That makes the app more useful than a calculator that only serves the person who already understands military retirement terminology. A household member who has never dealt with service pay can follow the conversation without needing to build a spreadsheet from scratch. I especially like this kind of use when the family is comparing two broad paths, such as continuing service for a while longer versus preparing for a civilian job sooner.
There is a practical boundary here. The app estimates military retirement pay; it does not turn that estimate into a full family financial plan. I would still keep separate figures for taxes, insurance, civilian earnings, savings, housing, education costs, and irregular expenses. The calculator can anchor the retirement-income discussion, but it should not be mistaken for a complete picture of what a household can spend.
A helpful habit is to write down the assumptions beside each result rather than saving only the final number. If I revisit the calculation weeks later, I want to know whether I changed service time, pay information, or simply remembered the original inputs incorrectly. This is one of the less obvious benefits of using a dedicated calculator: it encourages a defined scenario instead of a vague statement such as “retirement should be enough.”
One realistic evening with the calculator
Imagine a service member and partner reviewing their next few years after dinner. They are not ready to make a final decision, but they need to know whether a possible retirement path deserves serious attention. I would open the app, work through the relevant inputs together, and record the resulting estimate with a plain-language note describing what was entered.
The partner might then ask how the household budget changes if the service member works after leaving. That question is outside the calculator’s central job, but the estimate gives the couple a starting point. They can place it beside expected civilian income and recurring bills, then identify the gap that still needs research. If the estimate looks uncomfortable, they have found that early, while there is still time to adjust savings or investigate employment.
In that situation, the app is valuable because it reduces friction at the beginning of the conversation. It does not settle the conversation. I would regard a result as a prompt for the next action: verify the assumptions, check the applicable retirement rules, and test the household budget under conservative conditions.
Keeping personal inputs separate on a shared device
Household use also requires a little discipline. A shared phone or tablet can make the app convenient, but military and financial information should not be treated as casual family data. I would avoid leaving a completed scenario open when another person is about to use the device, particularly if the device is shared with children, guests, or anyone who does not need to see the figures.
Rather than assuming the app creates separate household profiles or protects each person’s scenarios, I would use a simple manual boundary: one person enters the information, the household discusses the result, and the device is cleared or returned to its normal owner afterward. That is not a feature claim; it is a sensible routine for any finance tool used on a shared screen.
This matters even more when two adults are comparing different service histories. Mixing one person’s inputs with another’s can produce a result that looks precise while representing nobody accurately. I recommend pausing before every new calculation and confirming whose situation is being modeled. A short note naming the scenario, without exposing unnecessary personal details, can prevent confusion when several estimates are discussed in one evening.
What setup feels like in practice
Military retirement calculations are sensitive to the quality of the information entered. Before using the app, I would gather the service details and pay information needed for the estimate instead of guessing from memory. If a value is uncertain, I would run a cautious scenario and a more optimistic one, clearly labeling both. That approach is more useful than pretending an uncertain input is exact.
The narrow design is helpful here. Because this is not a general budgeting app overloaded with spending categories, I can focus on the retirement question. The trade-off is that I must bring my own context. Someone expecting the app to explain every retirement system, personal tax outcome, or benefit interaction may find the experience too limited.
I would also avoid entering information while distracted. A shared household discussion can easily turn into a debate about the future, and it is tempting to change several inputs quickly just to see a larger result. That is fine for exploration, but I would separate exploratory calculations from the scenario used for an actual decision. Otherwise, a memorable number may be based on a casual change that nobody recorded.
For a first session, I would create one baseline estimate, save the assumptions in a note, and then alter only one major variable at a time. This makes the result easier to explain to a partner and makes the trade-off visible. If the estimate changes, I can identify why instead of relying on a series of undocumented taps.
Coordinating decisions without turning the app into the decision-maker
The best household role for this app is coordination. A service member may understand the career timeline, while a partner may understand the family’s cash flow or upcoming obligations. The calculator gives both people a shared object to discuss. That is more productive than one person announcing a retirement figure with no explanation of how it was reached.
I would use the result to organize questions into three groups. First, which inputs are certain? Second, which assumptions need official confirmation? Third, what would the household do if the estimate were lower than expected? This turns a calculator session into preparation for a broader decision rather than a search for a reassuring number.
There is also value in comparing scenarios verbally. For example, one person can describe the baseline while the other writes down the effect of changing the planned retirement timing or relevant pay assumption. Even when the app is used by one person at a time, the conversation can remain collaborative if the assumptions are shared clearly.
Still, I would be careful with coordination across households. A friend, relative, or adviser can help think through the result, but that does not mean they should receive every underlying detail. Sharing the estimate with context is different from handing over a phone containing all the entered information. The app supports a conversation; it does not define who should have access to the conversation.
Age, trust, and who should use it
The Everyone age rating makes the app approachable from an age-classification perspective, but retirement planning is still an adult responsibility. A teenager might learn something from watching a parent explain service and income planning, yet I would not expect a young user to understand the consequences of changing assumptions or relying on an estimate.
For older children, the app could support a useful lesson about how income estimates depend on inputs. I would demonstrate with a fictional or simplified situation rather than exposing sensitive household figures. The important lesson is not the final amount; it is the difference between a calculation and a confirmed entitlement.
Trust also matters between adults. If one person enters the information and presents the result, the other person should be able to ask how it was produced. I prefer opening the calculation together and reviewing the assumptions before discussing what the household can afford. That small step reduces the risk that the app becomes an authority in an argument.
I would skip this app for a child looking for an educational game, a family seeking parental-control tools, or anyone wanting a general money manager. Its purpose is much more specific. It makes sense for service members, veterans planning around retirement income, and household members who need to understand a military retirement estimate. It is not designed to replace a full budgeting platform or a formal benefits consultation.
What the rating and cost suggest about the experience
Military Retirement has a 4.7 average from around eight hundred ratings, with nearly three hundred written reviews, and it has passed ten thousand installs. Those figures suggest that the focused approach resonates with a meaningful group of users, while the written feedback can help a prospective buyer understand how others experience a specialized calculator.
The app costs $5.99, so I would judge it differently from a free utility I might open once and forget. The price is easier to justify if I expect to compare multiple retirement scenarios or use the calculator during an important planning period. If I only need one rough estimate and already have access to a trusted official calculator or adviser, paying for another tool may feel unnecessary.
That price also changes how I think about accuracy expectations. A paid calculator should save time and make a specialized task easier, but payment does not make an estimate official. I would still verify important assumptions through current military resources before making a career or household commitment.
Where it is stronger than ordinary alternatives
The usual alternative is a spreadsheet. A spreadsheet can be more flexible, especially for combining retirement income with taxes, civilian wages, investment withdrawals, and household expenses. It is also easier to customize for a complicated family situation. However, building the military-retirement portion correctly takes time, and a spreadsheet can hide an error behind a polished layout.
This app is stronger when I want a focused, repeatable estimate without designing the calculation myself. It is also easier to hand to a partner during a conversation because the purpose is immediately clear. The trade-off is that the app is not the place where I would maintain a complete long-term financial model.
Another alternative is an official government or military resource. That is the better choice when I need authoritative rules, eligibility interpretation, current policy context, or confirmation of an actual benefit. Military Retirement can complement that research by helping me frame questions and explore possibilities, but I would not use it to override official information.
General budgeting apps are another imperfect substitute. They are useful for tracking spending and setting goals, yet they usually do not make military retirement estimation the center of the experience. If the immediate question is “How does this service-related income estimate affect our plan?” this app is more direct. If the question is “Where did our money go this month?” a budgeting app is the better tool.
Version, platform expectations, and everyday friction
The current version is 2026.7, and the minimum operating-system requirement is 7.0. That makes the app accessible to devices running a relatively old supported system, which is useful if a household keeps an older phone for shared planning. I would still check the device’s compatibility before paying, especially if the app is intended for a secondary tablet or an aging family handset.
Because the app has a narrow job, the main friction is conceptual rather than decorative. Users need to know what they are trying to estimate and which information belongs in the calculation. Someone who wants a guided retirement course may find the experience abrupt. Someone who already knows the relevant details may appreciate not being buried under unrelated financial tools.
I also recommend treating every result as dated in your own notes, even when the app itself is convenient to reopen. Retirement planning changes as service circumstances and household priorities change. A result without its assumptions can become misleading later, particularly when a family compares it with a new estimate and cannot remember what changed.
My household verdict
I would recommend Military Retirement to a service member or household that needs a dedicated way to explore military retirement pay and is willing to verify important conclusions elsewhere. Its strongest quality is focus: it gives a shared household conversation a concrete starting point without pretending to be a complete financial-planning system.
I would buy it when I expected to test several scenarios, prepare for a discussion with a partner, or organize questions before checking official guidance. I would skip it if I wanted expense tracking, investment management, tax planning, or a comprehensive benefits explanation. Those needs call for different tools, and forcing them into this calculator would create frustration.
My final advice is simple: use one person’s information at a time, label each scenario, separate confirmed facts from guesses, and never let the displayed estimate end the research. The app is most valuable as a clear conversation starter, not as the final authority on a household’s future. Used that way, it earns its place on a shared planning device while keeping the responsibility for the decision where it belongs: with the people involved and the official sources they consult.
Gallery
Military Retirement Pros and Cons
- Provides clear retirement information for military personnel and veterans.
- Useful tools help estimate benefits and plan post-service finances.
- Covers important eligibility rules and retirement options in one place.
- Simple interface makes key information quick to find.
- Helpful for comparing retirement scenarios before making decisions.
- Some information may vary by country
- branch
- or policy updates.
- Benefit estimates may not reflect individual service records accurately.
- Advanced financial planning features may be limited.
- Users may need official sources to confirm final retirement figures.
- The app may be less useful for civilians or newly enlisted users.
Military Retirement Frequently Asked Questions
What is Military Retirement?
Military Retirement is an app designed to help service members, veterans, and their families understand and estimate military retirement benefits. It may provide access to retirement calculators, eligibility information, pension estimates, service-credit guidance, and related planning resources. The exact tools and content can vary by platform and app version, so users should review the description and available features before downloading.
Can Military Retirement calculate my estimated pension?
The app may help you estimate retirement pay by using details such as years of service, retirement system, rank, pay grade, and projected retirement date. However, any figure shown should be treated as an estimate rather than an official determination. Military retirement calculations can involve complex rules, special provisions, taxes, and policy changes, so users should confirm results with an official military finance or benefits office.
Who can use the Military Retirement app?
Military Retirement is generally intended for active-duty personnel, reservists, National Guard members, veterans, retirees, and people planning a military career. Family members may also find the information useful when reviewing household retirement planning. Some features could be more relevant to particular branches, service periods, or retirement systems, so check whether the app supports your specific circumstances before relying on its calculations.
Does Military Retirement provide official financial or benefits advice?
No application should replace guidance from an official military benefits agency, personnel office, financial adviser, or tax professional. Military Retirement can be useful for learning terminology, comparing scenarios, and preparing questions, but its information may not reflect your complete personal record or the latest regulations. Always verify eligibility, pension amounts, survivor benefits, healthcare options, and tax details through authoritative sources.
Is my personal information safe when using Military Retirement?
Before entering service history, birth dates, income details, or other sensitive information, review the app’s privacy policy and permissions. Avoid submitting passwords, Social Security numbers, official identification numbers, or documents unless the app clearly explains why they are required and how they are protected. Users should also confirm whether calculations are stored locally or transmitted online, and keep the application updated.














